Stock Market Week Ahead (Sep 28-Oct 2): Micron Earnings, PCE Inflation, and the Jobs Report That Decides an October Fed Hike
Week ahead Sep 28 to Oct 2: August PCE inflation and Micron earnings land Wednesday, Nike Thursday, and Friday's jobs report at 8:30am ET decides whether the Fed hikes in October or December.
TL;DR
- Last week the 10-year Treasury yield hit 5.18%, its highest since 2007, and the 30-year mortgage crossed 7%. Stocks rose anyway: the S&P 500 gained 1.2% on the week to 7,743.41.
- Market prices imply about a two-thirds chance the Fed raises rates again on October 28. Friday's jobs report is the last one before that vote.
- Wednesday, 8:30am ET: August PCE inflation, the Fed's preferred gauge. Last month's reading ran hot at 3.7% headline and 3.3% core.
- Wednesday, after the close: Micron earnings. The company forecast a record $50 billion of revenue for the quarter. The result could move the entire chip and AI sector, depending on Micron's forecast for the next quarter.
- Thursday, after the close: Nike earnings, with the stock close to its 52-week low after a Bank of America downgrade on Friday.
- Friday, 8:30am ET: the September jobs report. Economists expect 90,000 to 100,000 new jobs, against 162,000 in August.
More on $SPY: Stock Market Week Ahead (Sep 21-25): Costco, AutoZone, KB Home and a 5% Ten-Year →
The Board
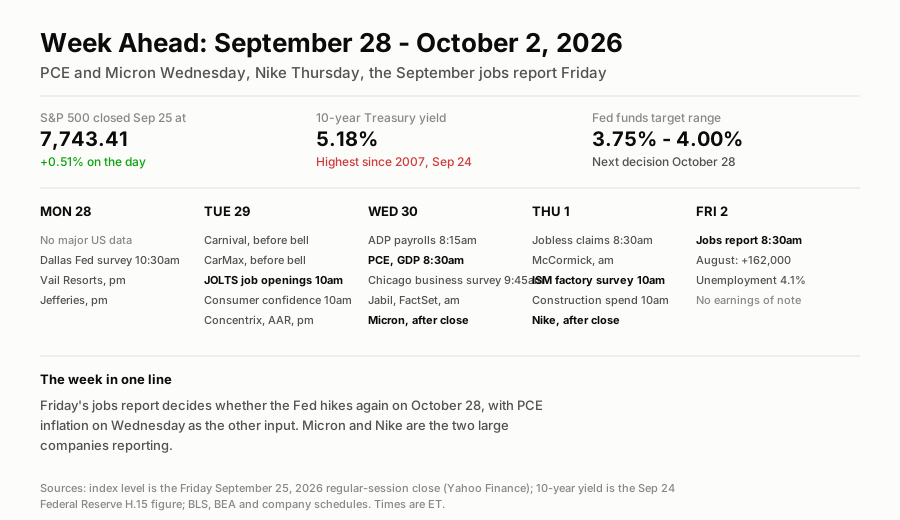
PCE and Micron on Wednesday, Nike on Thursday, the jobs report on Friday.
What Time Is the September Jobs Report?
8:30am ET on Friday, October 2, per the Bureau of Labor Statistics schedule. Economists expect 90,000 to 100,000 new jobs and unemployment near 4.1%. Bloomberg's survey has 90,000 and Trading Economics has 100,000, and Capital Economics is well below both at 50,000.
August came in at 162,000 against a 53,000 forecast, and the prior two months were revised up by a combined 55,000, per the BLS. The August jobs hub has where those jobs came from. There is no shutdown risk this time: Congress funded the government through December 11 at the start of the month, per Military Times.
Last Week: the 10-Year Treasury Yield Passed 5%, Mortgage Rates Passed 7%, and Stocks Went Up
Bond prices kept falling last week, which pushed yields up. The 10-year yieldThe 10-year Treasury yield is the interest rate the US government pays to borrow for ten years. Mortgage rates and most long-term borrowing costs are set off it, which is why a move in this one number reaches housing, corporate borrowing and stock valuations. reached 5.18% on Thursday and held that level into the close on Friday, per the Federal Reserve's H.15 release. Governor Barr said on Wednesday that further policy adjustments should be expected, per CNBC. Freddie Mac's 30-year mortgage rate moved to 7.03%, up from 6.95% a week earlier and 6.30% a year ago, per Freddie Mac.
Housing data held up better than I expected against the higher mortgage rate. New-built home salesNew home sales is the monthly government count of newly built houses sold, stated as an annual rate. It is the cleanest read on builder demand, because a new home is only bought when someone can afford the mortgage on it that month. jumped 6.4% in August to a 684,000 annual rate, against a 650,000 forecast. KB Home beat on both lines and held its delivery guide for the year, per its release. The stock still slipped after hours once the chairman called conditions weakening. Last week's edition has every result from the week.
Stocks just kept going up. The S&P 500 closed Friday's regular session at 7,743.41, up 1.2% on the week, and the Dow ended a three-week losing streak, per Yahoo Finance. AMD in particular did well. It crossed $600 on Monday and joined the $1 trillion market-cap club, per CNBC, and closed the week above $625. The sector heatmap shows which groups carried the index.
My read: stock investors see a 5% 10-year Treasury yield as the cost that comes with a strong economy. Friday's jobs report tests whether the economy is still strong enough to carry it. A poor report might dampen the optimism.
Friday's Jobs Report Decides Whether the Fed Hikes in October or December
The Fed's September projections pencilled in one more hike this year, at either the October 28 or the December 9 meeting. Roughly two-thirds of the market now expects an October hike, per CME's FedWatch tool.
Friday's number decides which month we get the hike. A second strong month of nonfarm payrollsPayrolls (nonfarm payrolls) is the headline number of the monthly jobs report: the net count of jobs US employers added or cut. It excludes farm work, which swings with the seasons rather than the economy. makes an October hike hard to skip. A print near 50,000, which Capital Economics has, makes a December hike more likely.
Wednesday's PCE inflation reading is the other input to whether the hike comes in October or December. July's PCEPCE (the Personal Consumption Expenditures price index) is the inflation measure the Fed officially targets at 2%. It covers a wider range of spending than CPI and weights items differently, which is why the two can disagree and why Fed officials quote PCE when the headlines quote CPI. price index ran hot, with a 3.7% headline and 3.3% coreCore inflation strips food and energy out of CPI or PCE, because those prices swing with the weather and the oil market rather than the economy. The Fed watches core as the cleaner read on underlying price pressure, even though people still pay for food and fuel., per the BEA. After those hot CPI and PPI readings, forecasters lifted August's core estimate to 0.3% for the month, which annualises near 3.7%. A 0.3% core print plus 100,000 jobs is a hike. A 0.2% print plus 50,000 jobs is a real debate.
Eight Fed speeches are scheduled this week, per the Fed's calendar, and none is by Fed Chair Kevin Warsh. The Fed hub tracks the odds, and the Fed calendar has the dates.
Micron Wednesday: a $50 Billion Revenue Forecast, for a Quarter That Runs 14 Weeks
Micron reports earnings after Wednesday's close. The company guided to $50 billion of revenue, give or take $1 billion, and adjusted earnings of $31.00 a share, give or take $1.00, per its June release. Gross margin was guided near 86%. Analysts want roughly $31.50 on $51 billion, the top of Micron's own range.
One adjustment to that revenue figure: the quarter is a week longer than usual. The $50 billion guide is about 21% above last quarter's $41.46 billion, but this quarter has 14 weeks against the usual 13, per Micron's 10-Q. So the weekly increase is about 12%. Still enormous, especially if it continues.
The stock closed Friday near $1,080. On September 16 this site logged a pass on selling Micron options into this print, with the stock at $929 and a 10.9% move priced. The reasoning: memory companies keep beating their own guides by huge margins, and their stocks have often swung past what options price, and not always in the direction a beat would suggest. Since that call, Micron has already risen about 16% without reporting anything. That call gets graded on Thursday.
My read: the revenue beat is close to a given. What I'd watch is the margin guide for next quarter. An 86% gross margin is the highest Micron has ever guided to, and any sign it has peaked matters more than a revenue miss. Micron has beaten and sold off before: it fell 22% from its highs after a record quarter in July. The August call on the stock was written at $877.
Nike Thursday: a 52-Week Low and a Fresh Sell Rating
Nike reports earnings Thursday after the close, with results at about 4:15pm ET and the call at 5:00pm, per the company. Analysts want about $0.45 a share on $11.3 billion of revenue, against $0.49 on $11.7 billion a year ago. Both lines shrink. Nike's own guide has revenue down low single digits for the first half of its fiscal yearA fiscal year is the 12-month period a company uses for its accounts, and it does not need to match the calendar: Dell's fiscal 2027 is mostly calendar 2026. That is why a 'fiscal Q2' can land in September., with Greater China the weakest region. Tariffs cost it $1.5 billion a year before offsets.
Bank of America cut the stock to Underperform on Friday with a $30 target, down from $47, per CNBC. The bank said the turnaround is taking longer than expected. Nike also left the S&P 100 on September 21 after nearly 18 years, replaced by Palo Alto Networks, per Fortune.
The one number that could change the view on Nike is its forecast for gross margin. Nike said it turns slightly positive this quarter, a quarter earlier than it had signalled. This site's August call, written at $41.70, was that the stock had not found a bottom. It is $35.75 now. I'd want China to stop shrinking before changing that view, and Thursday is the report that tests it.
The percentage after each company below is its implied moveThe implied move is how far the options market expects a stock to move on an event, up or down, worked out from options prices. A 12% implied move on a $50 stock means traders are paying for a swing to roughly $44 or $56. It is what is already priced in, so the stock has to beat it for an options bet to pay., the size of share-price swing that options prices pointed to for the results. Each figure is as of Friday's close, from the earnings calendar.
Monday, September 28
- No major US data.
- 10:05am ET: Fed Governor Barr on the economic outlook and housing.
- 10:30am: the Dallas Fed surveyThe regional Fed banks each survey businesses in their district every month about orders, shipments, hiring and prices. None moves markets on its own; together they are an early read on the national ISM and PMI numbers that follow. of manufacturers.
- After the close: Vail Resorts (implied move 10.0%), Jefferies (9.1%). Vail's quarter to July is its off-season, so the season-pass update matters more than the loss.
Tuesday, September 29
- Before the open: Carnival (call 10:00am ET, per the company), CarMax (implied move 12.9%).
- 10:00am ET: August JOLTSJOLTS (the Job Openings and Labor Turnover Survey) is a monthly US government report counting job openings, hires and quits. Payrolls says how many jobs exist; JOLTS says how many are on offer, which is why openings often turn before hiring does. job openings and September consumer confidence.
- Fed speakers: Barr at 12:40pm, Cook at 1:25pm, Waller at 3:00pm.
- After the close: Concentrix (implied move 20.2%), AAR (11.5%).
Wednesday, September 30
- 8:15am ET: ADPADP is one of the largest US payroll processors. Its monthly report estimates private-sector job growth from the payrolls it handles, and lands ahead of the official jobs report, so markets read it as an early preview. private payrolls for September.
- 8:30am ET: August PCE inflation, and the third estimate of second-quarter GDP. The second estimate was 1.5%, per the BEA. This release also starts the BEA's annual revision, so earlier quarters can move too.
- Before the open: Jabil (implied move 9.1%), FactSet (11.0%), Conagra (5.4%).
- After the close: Micron (call 4:30pm ET). Wednesday is also the last day of the third quarter.
Thursday, October 1
- 8:30am ET: weekly jobless claimsWeekly jobless claims count how many people filed for unemployment benefits, published every Thursday. They are the fastest official read on layoffs: monthly reports describe last month, claims describe last week.. 10:00am: ISMISM (Institute for Supply Management) surveys US businesses each month to track changes in demand, hiring, prices and overall business conditions. manufacturing for September.
- Fed speakers: Waller at 10:00am, Vice Chair Jefferson on the economy and monetary policy at 1:30pm, Cook at 3:30pm.
- Before the open: McCormick (implied move 8.6%), Acuity (9.5%).
- After the close: Nike, results around 4:15pm ET and the call at 5:00pm.
Friday, October 2
- 8:30am ET: the September jobs report. 10:00am: August factory orders.
- No earnings of note. The next SpaceX lock-up trancheA tranche is one scheduled slice of a lock-up release. Rather than freeing every insider share at once, an IPO prospectus can release them in steps on fixed day counts, so each tranche is a date when a set number of shares becomes sellable. is the following Friday, October 9, on the lock-up calendar.
The full list of economic data releases is on the economic calendar, and each morning's timetable is on /today.
The One-Line Read
Friday's jobs report decides whether the Fed raises rates in October or December, and Wednesday's PCE inflation is the other input. Micron and Nike are the two large companies reporting.
Next up:PCE inflation, Wednesday at 8:30am ET →
More on $SPY
$SPY · 2026-09-19
Stock Market Week Ahead (Sep 21-25): Costco, AutoZone, KB Home and a 5% Ten-Year
$SPY · 2026-09-18
Options Scorecard: A Reddit Put and a Nutanix Pass, Both Right at Expiry
$SPY · 2026-09-13
Fed Decision September 16 Hour by Hour: Retail Sales at 8:30am, Statement at 2:00pm, Warsh at 2:30pm
Updated Every Saturday
The Week Ahead
Every earnings date, Fed event and setup for the current trading week, on one page.
Refreshed Weekly
Earnings Calendar
Who reports next, when, and what consensus and the whisper expect.
The Week-Ahead Brief
Don’t miss next week’s setups. Get the Sunday brief.
Today's issue“Micron, PCE and the jobs report that decides October”
Every Sunday: next week’s earnings dates, Fed days and the trades worth watching, from the same desk that writes the week-ahead hub. Free, built for retail investors.