Applied Materials Earnings: Record Q3, a $700m Guide Beat, and the Stock Fell
Applied Materials posted record fiscal Q3 revenue of $9.12 billion and guided Q4 to $10.25 billion, roughly $700 million above consensus. The stock closed down 2.48% and fell again after hours.
Show 3 earlier updates
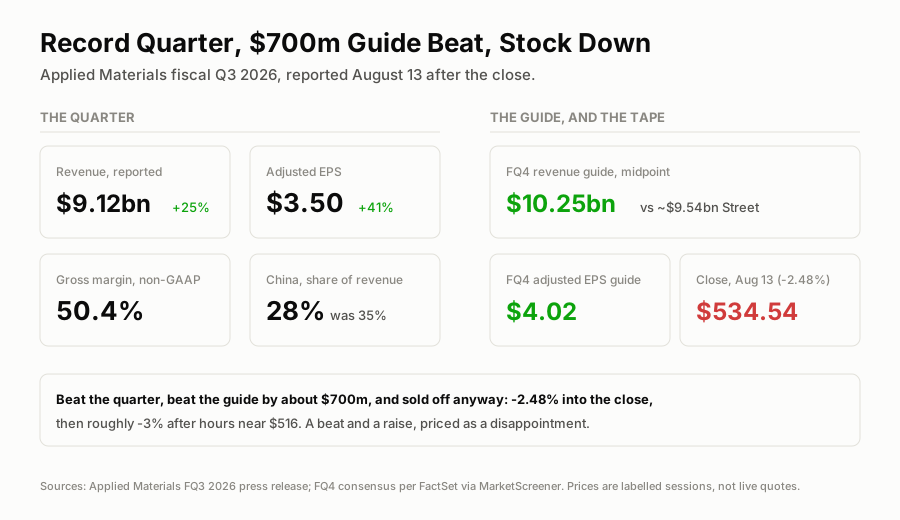
Beat, raised, and sold. The order book was never the argument against this stock; the multiple was.
TL;DR
- Applied Materials reports fiscal Q3 2026 results Thursday, August 13, after the close (date per multiple outlets; the company's own advisory page was unreachable for confirmation at writing).
- The guide is the consensus: management guided revenue of $8.95 billion plus or minus $500 million, up about 23%, and adjusted EPS of $3.36 plus or minus $0.20, up about 36% from $2.48, and the Street has settled exactly on the midpoints. The bar is not the print, it is the FQ4 guide.
- The demand backdrop got louder while the stock fell: Samsung says the memory shortage lasts into 2028 and is building capacity, TSMC raised 2026 capex to $60-64 billion, and AMAT itself has guided its semiconductor systems business to grow 30%-plus in calendar 2026 with advanced packaging up 50%-plus.
- The tape has been vicious: a June record, then a ~40% drawdown into the late-July chip selloff, then a 15% single-day rebound on July 30 in the memory relief rally. Monday's close sat around $508, still more than 30% below the high.
- The known cost: new US export restrictions that AMAT expects to remove $600-710 million of fiscal 2026 revenue, with China now roughly a quarter of sales versus ~40% in 2023.
More on $AMAT: Is Applied Materials a Buy Before Earnings? Not at 43x Into a 7.5% Move →
When Does Applied Materials Report Earnings?
Thursday August 13, after the close. It is the biggest semicap read between now and Nvidia on August 26, and the first since the memory complex turned. Next week's slate is in the earnings calendar.
The Board

The customers keep raising capex. The stock keeps crashing anyway. One of those is wrong.
The Guide Is Already the Consensus, So the Guide Is the Print
AMAT guided $8.95 billion and $3.36 in May and consensus sits precisely there, the pre-agreed-headline setup this season keeps repeating. What is not pre-agreed: the FQ4 guide, and whether management's own promise, semi systems up 30%-plus for calendar 2026, advanced packaging up 50%-plus, survives contact with export controls and customer scheduling. The last quarter was a record ($7.91 billion, 50% gross margin); records are the baseline now.
The Memory Argument Runs Through This Print
The reason AMAT belongs on this site's calendar: it is the arms dealer for the memory capex cycle we have been tracking since July, the dead-cat-bounce question included. The demand claims have only escalated: Samsung publicly sees the shortage into 2028 and is adding a Pyeongtaek fab, TSMC lifted capex to $60-64 billion, and every HBM roadmap requires more of exactly the deposition, etch and advanced-packaging tools AMAT sells. If those capex numbers are real, AMAT's FQ4 guide should show it; a soft guide from the toolmaker would be the first hard evidence against the whole memory thesis, worth more than any single memory maker's print.
China Is the Known Subtraction
The export-control arithmetic, as AMAT has framed it: a $600-710 million fiscal 2026 revenue hit from new license requirements, with China revenue already compressed to roughly a quarter of sales from ~40% in 2023. That number is guided-in, but any update to it moves the stock, in either direction: relief from license grants, or a wider definition of restricted tools.
The Options Angle
No current implied move was sourceable (circulating quotes trace to the May print), so no volatility plays are logged. Note the tape's own statement instead: this stock moved 15% in a single session on July 30 without any company news. Realised volatility in the semicap complex is running far above anything options normally price, which is the season's calibration lesson in its purest form.
Trade log
| # | Stance | Structure | Strikes and expiry | Cost or credit | Spot at writing | Implied move | Breakeven |
|---|---|---|---|---|---|---|---|
| 1 | Pass | Any pre-print options position | Aug expiries | Not sourced | ~$508, Aug 3 close | Not sourced | n/a; pass scored against the realised move |
| 2 | Conditional | Post-print long (shares or 1-2 month calls) if the FQ4 guide confirms the 30%+ systems trajectory | Struck off the Aug 14 open | Struck off the Aug 14 open | To be struck Aug 14 | n/a | Scored against the post-call entry if triggered |
The One-Line Read
Applied Materials reports with its customers publicly promising the biggest equipment spending wave in memory's history and its own stock priced 30% below June, and Thursday's FQ4 guide is where those two stories finally have to reconcile: the toolmaker's order book is the one place the memory supercycle cannot hide.
Next up:PCE inflation, Wed, Sep 30 at 8:30am ET →
More on $AMAT
Updated Every Saturday
The Week Ahead
Every earnings date, Fed event and setup for the current trading week, on one page.
Refreshed Weekly
Earnings Calendar
Who reports next, when, and what consensus and the whisper expect.
The Week-Ahead Brief
Don’t miss next week’s setups. Get the Sunday brief.
Latest issue, Sep 7“Week ahead in the stock market...”
Every Sunday: next week’s earnings dates, Fed days and the trades worth watching, from the same desk that writes the week-ahead hub. Free, built for retail investors.