Stock Market Week Ahead (Aug 31-Sep 4): Broadcom, Dell, and a Jobs Report Into 57% Hike Odds
Week ahead August 31 to September 4: Broadcom reports Wednesday, Dell and Palo Alto on Tuesday, and Friday's August jobs report lands into September hike odds near 60-66%.
TL;DR
- The August jobs report lands Friday, September 4 at 8:30am ET, per the BLS release schedule. A Reuters poll has payrolls at +58,000 and unemployment at 4.1%, level with July. July payrolls fell by 23,000.
- A September hike is priced at 60-66% as of Monday-Tuesday, up further from Friday's 57% print and from about 35% before Kevin Warsh spoke at Jackson Hole, even without new data over the weekend. That print and August CPI on the 11th are the two releases left that can move it. Full context on the climb.
- Broadcom (AVGO) reports Wednesday after the close, call at 5:00pm ET. Its own guide is $29.4bn of revenue and $16.0bn of AI semiconductor sales.
- Dell moved to Tuesday, September 1 (from Sept. 3rd). The company's advisory sets the call at 3:30pm CDT, which is 4:30pm ET, with results before it. Palo Alto Networks and MongoDB report the same afternoon.
- The Fed goes quiet on Saturday. The blackoutThe blackout is the quiet period before each Fed meeting when policymakers stop speaking publicly about rates and the economy. It exists so markets are not steered in the final days before a decision. for the September 15-16 meeting runs September 5 to 17. This is the last week a policymaker can answer the data in public.
What to Expect From the Stock Market This Week
Five labour-market reports arrive this week: JOLTSJOLTS (the Job Openings and Labor Turnover Survey) is a monthly US government report counting job openings, hires and quits. Payrolls says how many jobs exist; JOLTS says how many are on offer, which is why openings often turn before hiring does. on Tuesday, ADPADP is one of the largest US payroll processors. Its monthly report estimates private-sector job growth from the payrolls it handles, and lands ahead of the official jobs report, so markets read it as an early preview. on Wednesday, jobless claimsWeekly jobless claims count how many people filed for unemployment benefits, published every Thursday. They are the fastest official read on layoffs: monthly reports describe last month, claims describe last week. and Challenger job cutsChallenger, Gray & Christmas is a US employment firm that tracks layoffs. Its monthly report counts job cuts announced by US companies. on Thursday, and payrollsPayrolls (nonfarm payrolls) is the headline number of the monthly jobs report: the net count of jobs US employers added or cut. It excludes farm work, which swings with the seasons rather than the economy. on Friday. Markets spent most of August pricing out a September hike, but Warsh put it back in play on Friday - increasing hike oddsHike odds come from fed funds futures, contracts that pay out based on where the Fed's rate ends up. Their prices imply a probability, so 'a 57% chance' is what traders are betting, not a poll or a forecast.. Now each report could shift expectations for the Fed.
The S&P 500 closed Friday's regular session at 7,711.76, down 0.25% on the day and up 0.49% across the week. The Nasdaq finished at 26,402.42 and the Dow at 53,559.99, both higher on the week. Trading volumes in the indices were below the 2026 average and the VIXThe VIX measures how much movement options traders expect from the S&P 500 over the next 30 days, calculated from options prices. A low VIX means the market expects calm. near its low for the year. That is an August lull, and it likely ends this week. The sector heatmap is where a payrolls surprise will show up first.
The Board
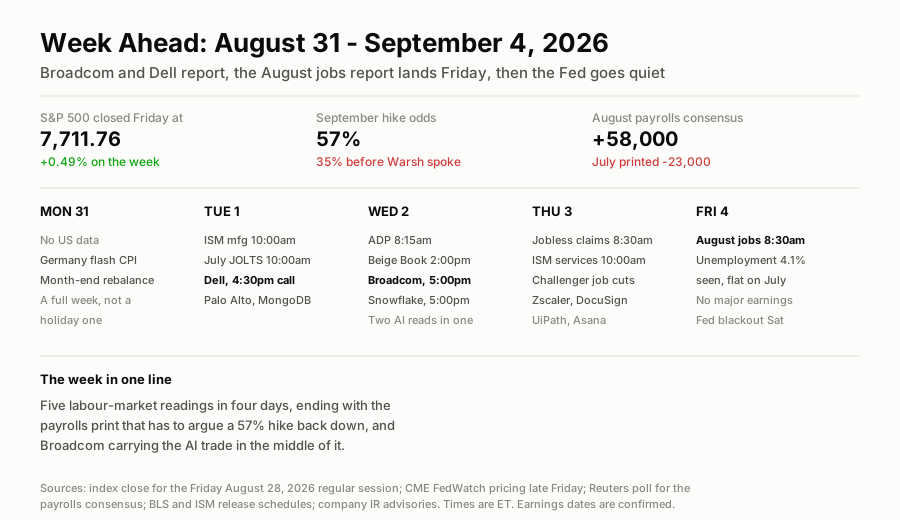
Five labour readings, and one key earnings report (AVGO).
Monday, August 31
Nothing on the US statistical calendar. Nor is there a holiday (other than a UK bank holiday). Labor Day falls on September 7 this year, the latest date it can, so this is a full five-session week. Germany's flash August CPI is the only print before the US open worth a look.
One date a lot of calendars still carry for Monday is not on Monday. Figma's final lock-up releaseAfter a company lists, insiders and early investors are barred from selling their shares for a set period, the lock-up. When it ends those shares can be sold for the first time, so a large release can pressure the stock., roughly 77.7 million Class A shares, is listed by most trackers as expiring August 31. The Extended Lock-Up Agreement filed with the SEC sets two triggers and takes whichever comes first. One is August 31. The other is the second trading day after Figma announces its June-quarter results. Figma announced those results on August 5, which put the release on Friday, August 7. The floatThe float is the number of shares actually available to trade, after subtracting what insiders and long-term holders cannot sell. New share supply matters relative to the float, not the total share count. before it was about 371 million shares, so the block was roughly 21% of the tradeable stock. Our IPO lock-up calendar states August 7.
Tuesday, September 1: JOLTS, ISM Manufacturing, and Dell
Updated September 1, 6:45pm ET: the morning data and both afternoon reports are in. ISM manufacturing PMI came in at 54.6% for August, down from July's 55.6% but still expansion territory, per ISM's release. July JOLTS job openings were 7.271 million, a touch below the roughly 7.3 million forecast, with June revised down to 7.2 million, per the BLS. Dell beat its own guide on every headline line and raised its full-year AI server guide from $60bn to $74bn; Palo Alto beat its guide too but swung to a GAAP loss on acquisition accounting and fell 5.2% anyway. Both hubs carry the full print below.
ISMISM (Institute for Supply Management) surveys US businesses each month to track changes in demand, hiring, prices and overall business conditions. manufacturing and the July JOLTS report both published at 10:00am ET. JOLTS was the one to watch, a July reading landing four days before the August payrolls number, since job openings have often been the first sign that the labour market is turning. Neither moved the picture much: manufacturing cooled a point and openings missed by a rounding error.
Dell reported fiscal Q2 after the close, with the call at 4:30pm ET. It had taken in $24.4bn of AI orders last quarter against $16.1bn shipped, and its full-year guidance looked like it implied shipments would slow from here. It reported the opposite: $16.4bn shipped, $60.9bn of new orders, and the full-year AI server guide raised from $60bn to $74bn.
Palo Alto Networks reported the same afternoon, with its webcast at 4:30pm ET. Its guidance had pointed to 32% revenue growth but only 1% to 3% earnings growth; it beat both, then reported a GAAP net loss on CyberArk and Chronosphere acquisition accounting and fell 5.2% regardless. MongoDB reported afterwards, beating on revenue and EPS and raising guidance, then falling about 13% in after-hours on a stock priced for more.
Wednesday, September 2: Broadcom
Updated September 2, 6:50pm ET: ADP came in soft, the Beige Book called growth modest, and both after-close prints beat their guides. ADP's August report showed private payrolls up just 38,000, below the roughly 47,000 forecast and down from a revised 46,000 in July, per ADP's own release. The Fed's Beige Book described economic activity as up modestly since early July, with employment rising only slightly and prices increasing moderately in most districts, per the Fed's own Beige Book page, as reported by Bloomberg. Broadcom beat its own $29.4bn revenue and $16.0bn AI semiconductor guide (actual: $29.6bn and $16.7bn) and still sold off in after-hours trading, down about 3.6% to roughly $354 as of 5:00pm ET on a Q4 guide of $34.8bn. Snowflake beat its guide by a wider margin (product revenue $1.49bn against a $1,415m-$1,420m guide) and rose as much as 22% in after-hours trading. Both hubs carry the full print below.
ADP’s August jobs report arrives at 8:15am ET, followed by the Fed’s Beige BookThe Fed’s Beige Book is a report on how the US economy is doing across the Federal Reserve’s 12 districts. It covers things like jobs, wages, prices, consumer spending and business activity, using surveys and conversations with businesses. at 2:00pm. Then comes the week’s main event. Broadcom reports fiscal Q3 after the close, with its call at 5:00pm ET. Broadcom has guided for $29.4bn in revenue and $16.0bn from AI semiconductors, up more than 200% from a year ago. As we just saw with NVDA this week, even crushing estimates is no guarantee the gap-up holds.
That $16 billion has been guided before. Broadcom put the same number out for the July quarter, delivered $10.8bn, re-guided to $16bn, and the stock fell about 3% on it. AVGO closed Friday near $368.
The comparison is unhelpful. Nvidia guided its October quarter to $108bn, and its chief executive put fiscal 2028 growth near 70%. Reuters framed this week's question as whether Broadcom can give investors the same confidence about future growth. NVDA closed Friday at $217.55, down ~4.5%, giving back half of Thursday's post-earnings gain.
Snowflake reports the same hour, product revenue is guided at $1.42bn, with a growth rate the company itself guided down four points.
Thursday, September 3: Jobless claims, ISM Services and Software earnings
Updated September 3, 6:55pm ET: services data ran hot, and the software earnings split on guidance rather than the print. Initial jobless claims rose to 206,000 for the week ended August 29, up from the prior week’s revised 204,000 and above the 205,000 forecast, per the Labor Department’s data. ISM services PMI jumped to 55.4% in August from July’s 54.1%, per ISM’s own release, with the Prices Index at 72.6%, up from 70.3% and still the hottest line in the report. Challenger, Gray & Christmas counted 52,881 August job cuts, up 58% from July’s 33,429 but down 38% year over year, per the firm’s own report.
Zscaler and DocuSign beat their own guides and rose after hours; UiPath and Asana beat revenue estimates and fell on soft guidance. Zscaler’s fiscal Q4 revenue hit $898.2 million, above its own $875 million-$878 million guide, with non-GAAP EPS of $1.19 against a $1.08-$1.09 guide, confirmed by the SEC 8-K exhibit and CNBC. The stock closed the regular session up 2.94% at $177.80, then traded around $176.24 in after-hours as of 6:36pm ET, still moving. DocuSign’s fiscal Q2 revenue was $875.7 million, above its $865 million-$869 million guide, with non-GAAP EPS of $1.16 against a $1.08 consensus, per DocuSign’s release. It raised its ARR growth outlook to 8.5%-9.0% from 8.0%, and the stock closed up 0.89% at $65.97 before trading around $68.43 in after-hours as of 6:26pm ET. UiPath’s fiscal Q2 revenue was $410.3 million, above its own $395 million-$400 million guide, with non-GAAP EPS of $0.15 matching guidance and raised its full-year revenue guide to $1.789 billion-$1.794 billion, per the company’s release and Benzinga. The stock closed up 1.28% at $18.22, then fell to around $16.90 in after-hours as of 6:39pm ET, on a third-quarter outlook investors read as too modest to hold a 40% pre-print rally. Asana’s fiscal Q2 revenue was $216.4 million, above its own $213 million-$215 million guide, with non-GAAP EPS of $0.10 against a $0.09 consensus, per Asana’s release; its third-quarter EPS guide of $0.08 sits a cent below consensus. The stock closed up 2.96% at $10.09, then fell to around $8.85 in after-hours as of 6:32pm ET. All four after-hours prints are still moving into Friday’s open; grade them on the settled close, not tonight’s tick.
Weekly jobless claims at 8:30am, ISM services at 10:00am, with Challenger’s August job-cut report around the same time. Services inflation is still the Fed’s main concern. A strong ISM services reading would make a rate hike more likely, while a weak manufacturing reading would do less to change that.
Zscaler, DocuSign, UiPath and Asana report after the close. Times for the full week are on the earnings calendar.
Friday, September 4: 8:30am August Employment
The August Employment SituationThe Employment Situation is the US government’s main monthly jobs report. Unlike JOLTS, ADP, jobless claims and Challenger, it gives the official count of jobs added or lost, the unemployment rate, wage growth and labour-force participation. publishes at 8:30am ET. Reuters expects +58,000 payrolls and 4.1% unemployment. Other forecasts predict 60,000 and 4.2%. In July, payrolls fell by 23,000, and the previous two months were revised down by a combined 103,000. Unemployment also fell, but mainly because fewer people were looking for work.
The market is more sensitive to a strong jobs report now. A month ago, weak jobs data made a September rate hike less likely. Now markets put the chance of a hike at 60-66%, up further since Friday even with no new data over the weekend, while the Fed chair says inflation has not improved much. A weak jobs report would need to change that view. A strong one would make a hike look more likely. The jobs hub carries the scenarios and the Fed hub tracks the runway to the 16th.
The One-Line Read
Friday's payrolls print is the last thing the Fed hears before it makes its decision. It has to argue a 60-66% hike back down, not up.
Next up:CPI, tomorrow at 8:30am ET →
More on $SPY
$SPY · 2026-10-10
Stock Market Week Ahead (Oct 12-16): JPMorgan and the Big Banks, September CPI, TSMC, and the Last Fed Speeches Before October 28
$SPY · 2026-09-27
Stock Market Week Ahead (Sep 28-Oct 2): Micron Earnings, PCE Inflation, and the Jobs Report That Decides an October Fed Hike
$SPY · 2026-09-25
Options Scorecard: No New Grades This Week, and an Analog Devices Round Trip
Updated Every Saturday
The Week Ahead
Every earnings date, Fed event and setup for the current trading week, on one page.
Refreshed Weekly
Earnings Calendar
Who reports next, when, and what consensus and the whisper expect.
The Week-Ahead Brief
Don’t miss next week’s setups. Get the Sunday brief.
Latest issue, Oct 11“September CPI, the big banks and TSMC: earnings season starts”
Every Sunday: next week’s earnings dates, Fed days and the trades worth watching, from the same desk that writes the week-ahead hub. Free, built for retail investors.